


“In the long run, the actions of producer countries could become another factor pushing gold prices higher.”
“In the long run, the actions of producer countries could become another factor pushing gold prices higher.”
Contents
-
Laos Wants the Refining Business
-
The Tax Changes the Export Decision
-
Who Holds the Reserves?
-
The Refiner Feels It First
-
Rates Still Matter
Authored by VBL of GoldFix
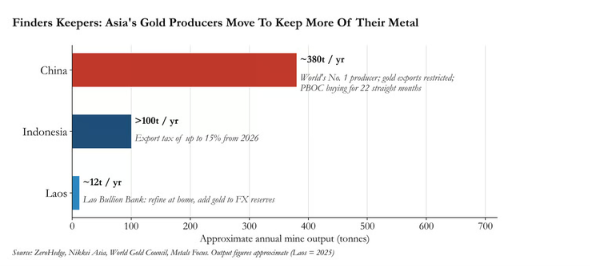
Gold-producing countries want more of the gold they mine to be refined, held and used at home. Indonesia taxes exports. China restricts gold leaving the country. Laos is building the facilities to process its own production. We have covered these policies because they change who gets the metal and who earns the money from it. Each government is protecting its resources and the businesses that depend on them.
Miki Kamiyama’s Nikkei Asia article, Asian gold producers begin hoarding domestic supplies after price rises, follows these policies across Asia and Africa, including the domestic buyers and facilities that make retaining gold possible.
Laos Wants the Refining Business

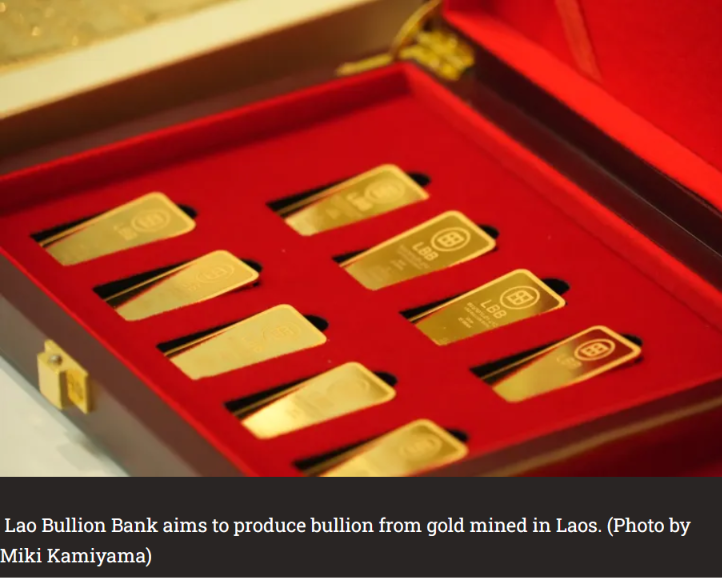
In 2024, the government established the Lao Bullion Bank, a specialized gold bank jointly capitalized by local companies.
It is using the institution as the hub of a rapid expansion of domestic precious-metals market infrastructure, including refining capacity.
The initiative aims to increase gold’s share in Laos’s foreign-exchange reserves, while giving citizens a trusted venue to buy and sell gold and preserve their savings.
The bank signed a memorandum of understanding with the Japan Bullion Market Association in January for help developing its precious-metals market. We covered the Hong Kong - Laos gold corridor agreement on July 20, 2026, linking qualified Lao owners with Hong Kong refining and clearing facilities. Laos is choosing foreign partners as it builds its own capacity.
Hong Kong and Laos Sign Gold Corridor Agreement

GFN - HONG KONG: Hong Kong and Laos have signed a memorandum of understanding establishing a gold market cooperation framework, opening the city’s accredited refining network to qualified Lao gold owners and linking them to its clearing infrastructure.
For us, the important change is what happens after the mine. Ship ore abroad and someone else gets paid to refine it. Produce bullion locally and the processing income stays home. The bar can then go to a citizen saving in gold, to the central bank or to an overseas buyer. Laos gets a say in where its production goes after extraction.
The exporter has to compare what is left after tax with what a domestic buyer will pay. Keep the foreign price unchanged and the tax reduces the proceeds from exporting. A local buyer can then compete without matching the full overseas price. That is how the government makes keeping gold at home more attractive.
Breaking: Indonesia Tariffs Gold Exports

Indonesia will introduce a new export duty on gold products by the end of next year, marking a major policy shift for one of the world’s top producers as the government pushes to expand domestic refining and processing capacity. The announcement triggered immediate declines in gold-linked equities.
China produces a little over 380 tonnes a year, roughly a tenth of global mine output, and still imports substantial quantities. Nikkei describes restrictions on taking gold out of the country and records a 20-tonne PBoC addition in August, its 22nd consecutive month of net purchases. China has both an official buyer adding to reserves and restrictions on metal leaving.
Madagascar’s central bank buys domestic production through official channels. Ghana is working with the WGC to curb illegal mining and improve gold supply chains. Both want more of the benefit from their own resources, though the effect on trade differs. A central-bank purchase retains metal. Bringing unofficial production into legal channels can increase the gold available through legitimate trade.
We would keep that distinction in mind when judging the supply effect. A new refinery can earn domestic income and still export every bar it produces. Foreign supply tightens when restrictions or competing domestic purchases reduce what leaves. The mine can produce just as much gold while an overseas refiner receives less of it.
One reason producing countries are taking a closer look at their own gold is waning confidence in the U.S. dollar as the world’s reserve currency.
Dollar-denominated assets belonging to countries at odds with Washington have been frozen under sanctions, reinforcing the view that excessive dependence on the currency carries risks.
“As the dollar-centered structure of global financial markets comes under scrutiny, gold is gaining importance as an asset insulated from the political and fiscal policies of any single country,” said Geullim Yum, director of Japan foreign exchange and commodity sales at banking multinational ANZ.
BRICS Central Banks Cut LBMA Out

We covered these purchases in BRICS Central Banks Cut LBMA Out on July 16, 2025. Central banks were paying local miners in local currency, acquiring gold without first spending another reserve asset abroad. For the miner, the state is now a buyer. For the foreign refiner, it is competition.
Our June 24, 2026 Thesis: China’s RMB Internationalization via Gold Collateral, developed with Eric Yeung, examined how gold could support financing. A lender needs to know who owns the bar, where it is held and how ownership can be transferred. Refining and gold-banking facilities help put those arrangements in place. Lending against the metal would be a further step.
Continues here unlocked


